This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:
You will not be guaranteed Negative Balance Protection
You will not be protected by FCA’s leverage restrictions
You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
You will not be protected by Financial Services Compensation Scheme (FSCS)
Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.
Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.
If you would like to proceed and visit this website, you acknowledge and confirm the following:
1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
4.Investing through this website does not grant you the protections provided by the FCA.
5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.
Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.
By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.
Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.
Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.
If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.
By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.
Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.
Post-NFP Reality Sets In; Uncertainty Remains as Tensions Persist
Post-NFP Reality Sets In; Uncertainty Remains as Tensions Persist
shawn
Ultima Markets Daily Market Insights – 6 April 2026
Global markets are opening the new trading week attempting to digest the fallout from Friday’s critical US Non-Farm Payrolls (NFP) report, whilst keeping a highly anxious eye on the Middle East. The macroeconomic landscape remains incredibly challenging for risk assets, as the reality of a restrictive Federal Reserve collides with persistent geopolitical threats.
Post-NFP Outlook: “Higher for Longer” is Here to Stay
Friday’s employment data delivered a clear and undeniable message: the US labour market remains stubbornly resilient. This robust NFP print has effectively slammed the door on any lingering hopes for an imminent dovish pivot from the Federal Reserve.
March Non-Farm Payrolls: +178K vs +60K consensus
March Unemployment Rate: 4.3% vs 4.4% Prior
Average Hourly Earnings: Cool to 3.5% YoY & 0.2% MoM
With job creation holding strong and wage pressures simmering, the central bank has the exact justification it needs to maintain its restrictive “Higher for Longer” interest rate policy. Consequently, US Treasury yields remain highly elevated, acting as a massive gravitational pull on global liquidity and severely suppressing risk appetite across the board.
US Dollar, EUR/USD, and Gold Outlook
The US Dollar has emerged as the undisputed victor of this macroeconomic environment, heavily supported by its dual status as a high-yielding asset and the ultimate geopolitical safe haven.
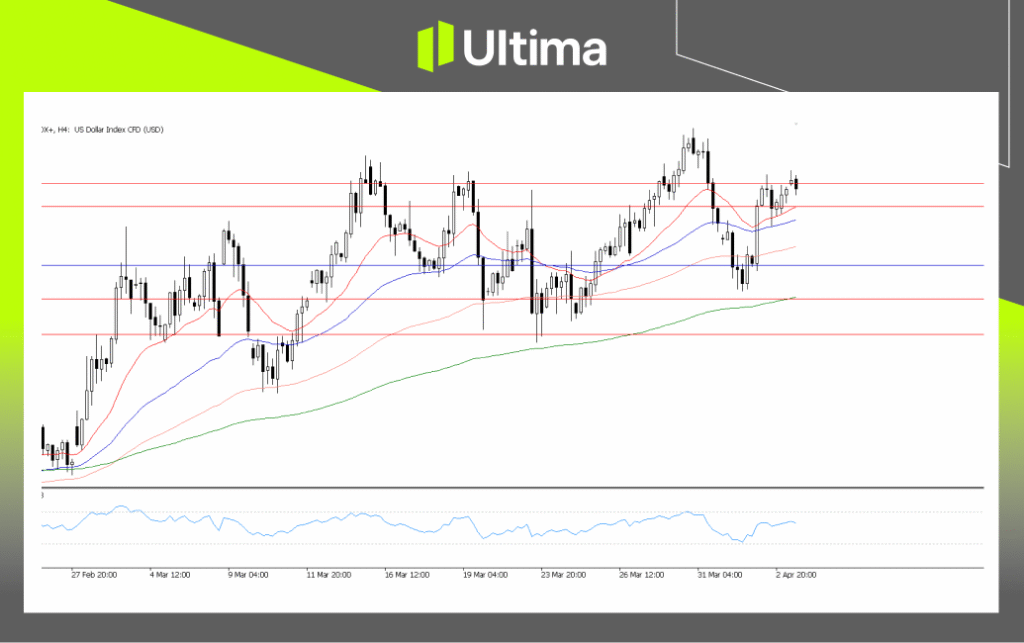
USDX, H4 Chart | Ultima Markets MT5
The US Dollar Index (USDX) has capitalised on the NFP momentum, aggressively challenging and attempting to consolidate near the massive 100.00 psychological resistance zone. The outlook for the Dollar remains the same; if bulls can firmly establish 100.00 as structural support this week, it will trigger a devastating wave of selling pressure across all major currency counterparts.
EURUSD Outlook
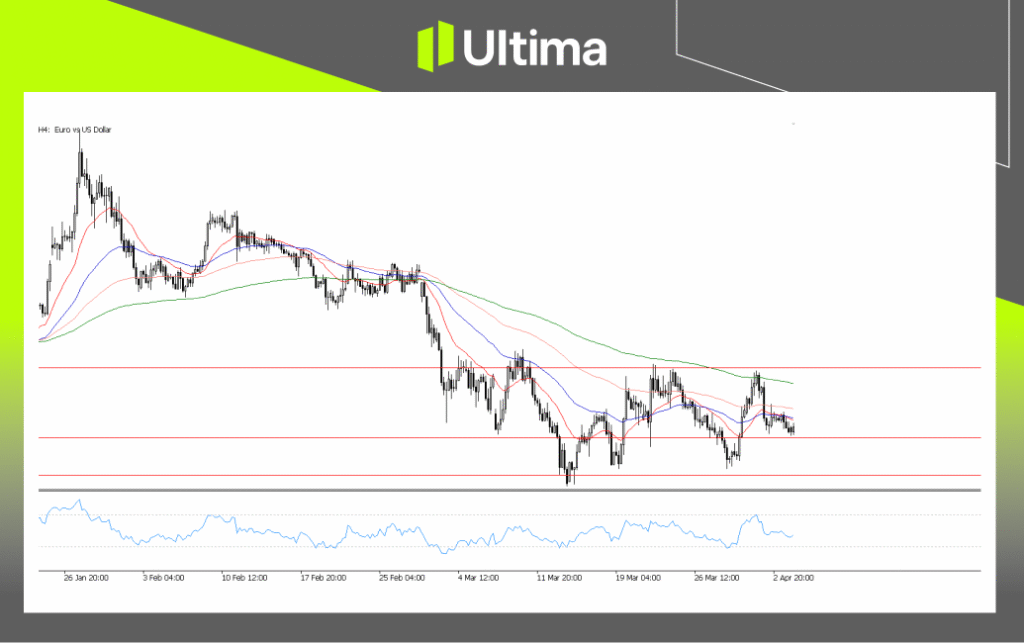
EURUSD, H4 Chart | Ultima Markets MT5
Bearing the brunt of this Dollar dominance is EUR/USD. However, the Euro’s intrinsic strength has kept the pair relatively steady. The pair is currently fighting for its life near the critical 1.1500 support floor.
Technically, we need to see a definitive daily close below this level to open the trapdoor for a much deeper bearish continuation. But as the price action suggests in both EUR/USD and the Dollar Index, the EUR/USD downside may be temporarily capped at this point.
GBPUSD Outlook
The British Pound is failing to withstand the sheer gravitational pull of the surging US Dollar. Following Friday’s robust NFP data, the fundamental divergence between the Federal Reserve’s cemented “Higher for Longer” stance and the Bank of England’s more precarious economic balancing act is becoming glaringly obvious to traders.
While the Bank of England continues to battle its own sticky domestic inflation, the overarching global flight to safety and the spike in US Treasury yields are completely draining capital away from Sterling.
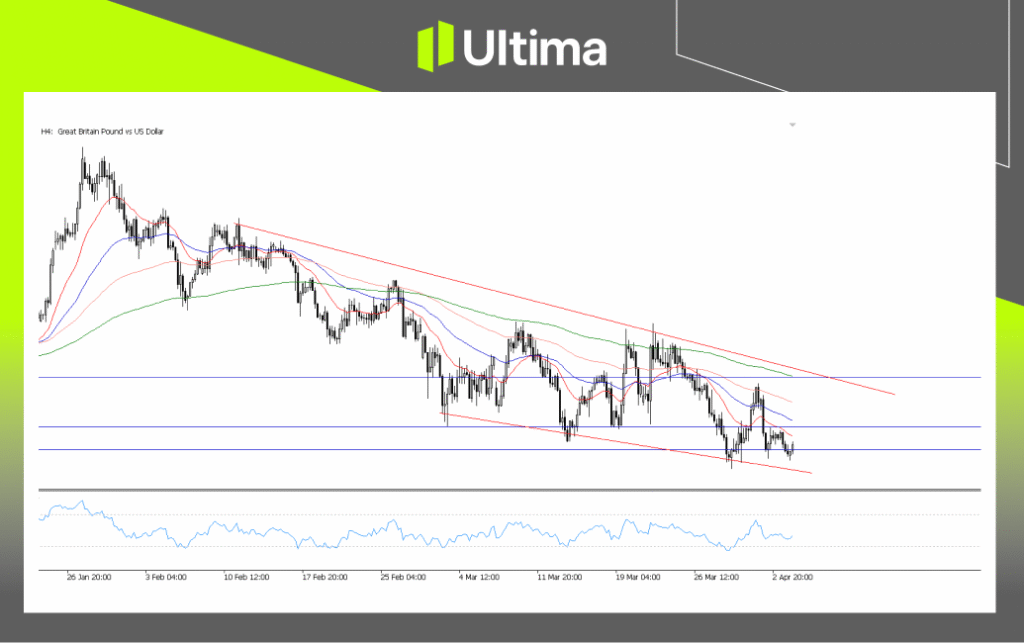
GBPUSD, H4 Chart | Ultima markets MT5
Technically, GBP/USD is facing a severe structural test. The pair has been aggressively driven down to challenge the massive 1.3200 support zone. This is a “make or break” level for the near-term trend.
Meanwhile, the falling wedge pattern will be the key near-term focus for traders. Until there is a definitive breakout of this falling wedge, the pair retains a bearish structure and remains open to a deeper plunge.
US-Iran War Updates: Continues to Weigh on Energy Shock and Outlook
Compounding the pressure from the bond market is the ongoing geopolitical crisis. Over the weekend, the US-Iran conflict remained locked in a tense and volatile stalemate. With no verifiable diplomatic breakthroughs, the fundamental threat to Middle Eastern energy infrastructure and global supply chains remains entirely active.
Because the market cannot confidently price out the “war premium”, energy prices remain dangerously elevated. This creates a toxic stagflationary environment—where high oil prices feed sticky inflation, forcing the Fed to keep rates high, which in turn chokes off broader economic growth.
US Indices Outlook: Vulnerable to the Downside
The overarching “risk-off” environment continues to heavily punish US equities. The toxic blend of surging borrowing costs and the looming threat of an energy-driven inflation spike leaves institutional buyers with very few reasons to confidently buy the dip.
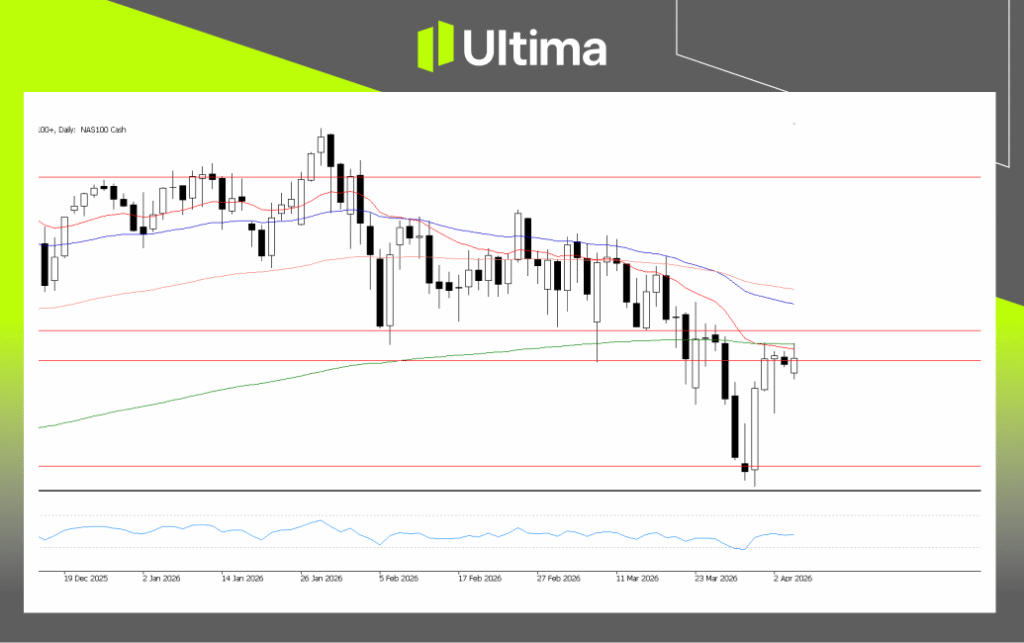
NAS100, Daily Chart | Ultima Markets MT5
Despite the rebound, the Nasdaq 100 remains trapped in near-term bearish structures. The NAS100 is facing heavy resistance at its 24,000 pivot zone.
Until there is a definitive de-escalation in the Middle East, a massive cooling of US Treasury yields, or a definitive reclaim of the 24,000–24,300 zone, the broader path of least resistance for equities remains tilted firmly to the downside.
Traders will likely continue to treat any intraday relief rallies as premium opportunities to sell.
What to Watch Today
Geopolitical Headlines (All Day): The market remains purely headline-driven. Any sudden confirmation of military escalations or disruptions to energy infrastructure in the Middle East will instantly spark extreme volatility across Oil, Gold, and the US Dollar.
Fed Official Speeches: Following Friday’s NFP data, markets will closely parse commentary from Federal Reserve officials to gauge exactly how comfortable they are with the current labour market resilience amidst surging energy risks.
Disclaimer
Comments, news, research, analysis, price, and all information contained in the article only serve as general information for readers and do not suggest any advice. Ultima Markets has taken reasonable measures to provide up-to-date information, but cannot guarantee accuracy, and may modify without notice. Ultima Markets will not be responsible for any loss incurred due to the application of the information provided.
Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where access is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdiction.
By clicking ‘Acknowledge’, you confirm that you are entering this website solely on your own initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.