This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:
You will not be guaranteed Negative Balance Protection
You will not be protected by FCA’s leverage restrictions
You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
You will not be protected by Financial Services Compensation Scheme (FSCS)
Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.
Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.
If you would like to proceed and visit this website, you acknowledge and confirm the following:
1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
4.Investing through this website does not grant you the protections provided by the FCA.
5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.
Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.
By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.
Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.
Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.
If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.
By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.
Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.
How the RBNZ’s “Hawkish Hold” Reshaped the Kiwi Outlook?
How the RBNZ’s “Hawkish Hold” Reshaped the Kiwi Outlook?
shawn
Executive Summary
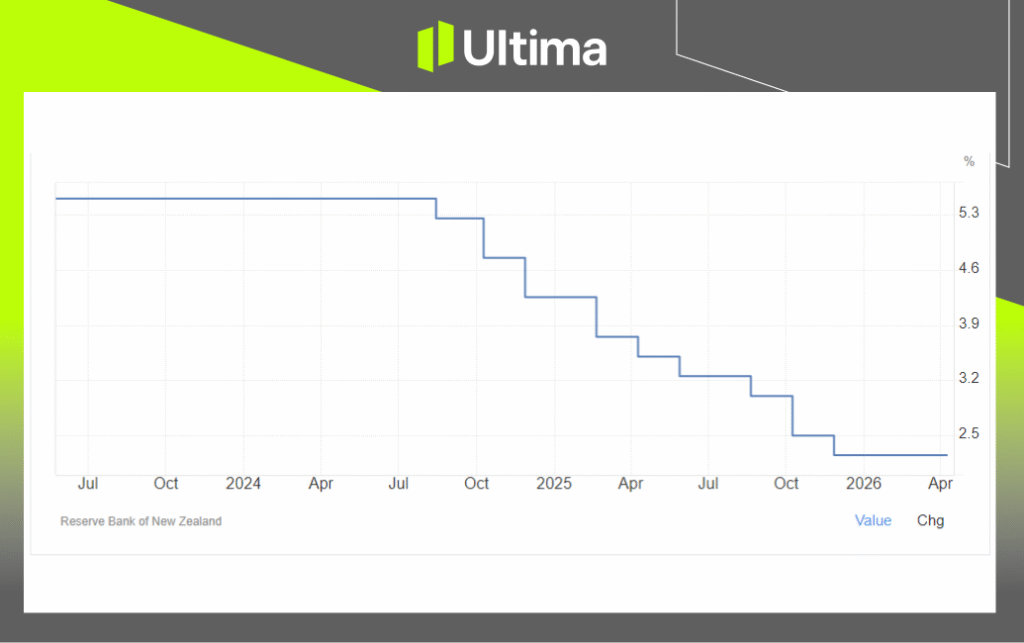
On Wednesday, April 8, 2026, the Reserve Bank of New Zealand (RBNZ) opted to maintain the Official Cash Rate (OCR) at 2.25%. While the “hold” was widely anticipated by institutional economists, the accompanying Monetary Policy Review (MPR) was significantly more hawkish than the market had priced in.
Faced with a looming inflation spike driven by the Middle East conflict and a fragile domestic recovery, Governor Anna Breman’s committee chose a path of “vigilant patience.” This analysis explores how this decision has effectively killed off hopes for further rate cuts in 2026 and what it means for the NZD’s trajectory against major pairs
RBNZ Decision: A Hawkish Hold
The RBNZ’s decision to keep the OCR at 2.25% must be viewed through the lens of the “Supply-Side Crisis.” The Committee noted that while the domestic economy remains in a state of “significant spare capacity” (with an output gap of -1.5%), the external environment has turned hostile.
RBNZ Kept Rate Hold at 2.25% for 3 Consecutive Meeting | Chart Source: TradingEconomics
The Inflation Forecast Shock
The most striking element of the release was the RBNZ’s new inflation projection. The bank now expects headline CPI to surge to 4.2% in the June 2026 quarter, a massive jump from the 3.1% recorded in December 2025. However, they expect this to be a “near-term spike” rather than a permanent shift, provided expectations remain anchored.
The Culprit: Sustained disruptions in global oil and gas supplies due to the Middle East conflict.
The Mandate: Despite the target band being 1–3%, the RBNZ is choosing to “look through” this immediate spike, betting that the high OCR (relative to historic lows) will eventually dampen demand enough to bring prices back down without a fresh hike.
Remarks From Press Conference
Despite not hinting at any hikes on the inflation forecast show, RBNZ’s Breman did admitted that the committee “discussed raising rates at today’s meeting” on the post press conference. While they ultimately chose a hold, she emphasized that “tightening could be at every meeting or every other meeting” depending on the data.
The Key statement also includes:
The “Vigilance” Stance: She explicitly stated that they were “not close to raising rates today” (no strong advocates for a hike this time), but warned that any sign of “second-round effects”—where rising fuel prices lead to higher wage demands—would trigger “decisive and timely” hikes.
The Middle East Factor: Breman noted that events in the Middle East have “materially altered the outlook.” However, she added a caveat: “If oil prices keep falling, our inflation forecast would be on the high side.”
Financial Conditions: She observed that financial conditions have already tightened (wholesale and mortgage rates have been creeping up), which she believes will help dampen growth and inflation without requiring immediate RBNZ action.
While no explicitly say raise rate, but the forward guidance on the inflation and “vigilance stance” put the consensus view to a “hike” expectation forwards. Previously, the market expected the RBNZ to stay on hold until 2027. But for major banks like Westpace have pulled their hike forecasts forward to September 2026.
The Governor defined the current “Neutral Rate” (where the economy is neither stimulated nor restricted) as a range with a 3.0% midpoint. Given the OCR is currently at 2.25%, the RBNZ is technically still in an “accommodative” or “easy” position, which explains why they are so quick to discuss hikes.
The Yield Divergence: NZD vs. AUD & USD
Despite the RBNZ’s hawkish pivot, the New Zealand Dollar faces a steep uphill battle in the global “Carry Trade” hierarchy. The fundamental challenge for the Kiwi is the massive interest rate differential (yield gap) with its closest peers.
While Governor Breman discussed hiking toward a higher neutral rate, the Reserve Bank of Australia (RBA) is already sitting at 4.1%. This 185 basis point advantage for the Aussie Dollar has pushed AUD/NZD to 12-year highs near 1.2115. Even a hawkish RBNZ is currently a “low-yield” central bank compared to the RBA.
The Greenback Dominance: With the US Federal Reserve also maintaining a restrictive stance near 4.75%, the NZD/USD is essentially a “negative carry” trade for many institutional investors.
Analyst Insight: The RBNZ’s hawkishness is currently acting as a floor for the currency rather than a rocket. It prevents a total collapse of the Kiwi, but until the RBNZ actually delivers a hike (likely September), the path of least resistance for AUD/NZD remains titled to the upside, while NZD/USD likely driven by broad dollar strengthen.
Technical Outlook for NZDUSD & AUDNZD
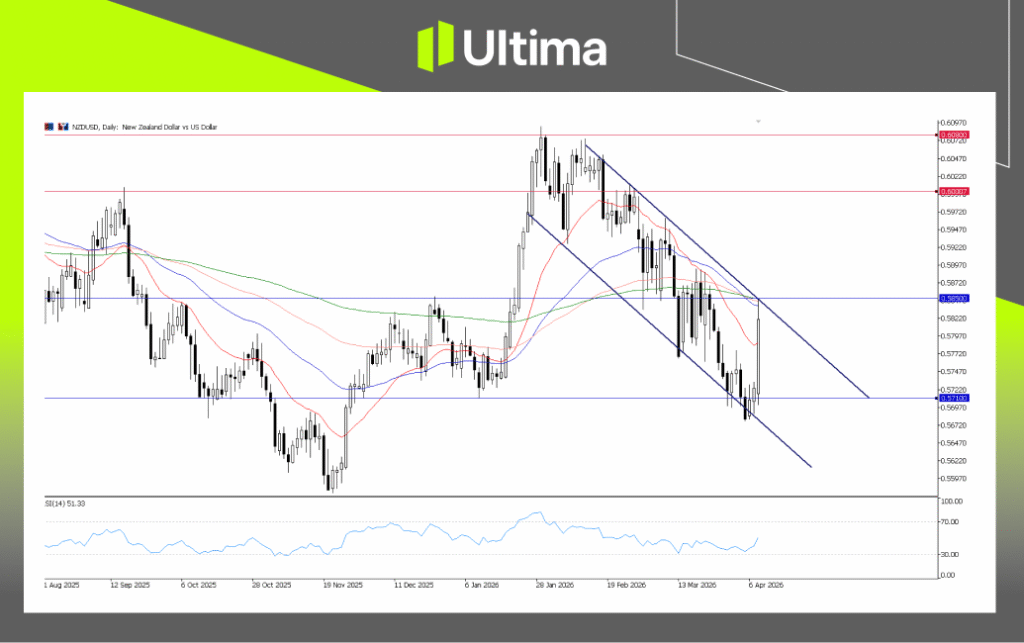
The immediate market reaction to the April 8 decision and the weaker dollar on middle east tension eased saw NZD/USD bounce off its multi-month lows. However, the pair remains trapped in a long-term bearish channel.
NZDUSD, Daily Chart | Ultima Markets MT5
The first major hurdle for the pair is the 0.5850 level. A decisive daily close above this marker would signal that the “RBNZ Hawkish Pivot” has developed real legs. Without such a breakout, the NZD/USD is unlikely to generate the upside momentum necessary to challenge the psychological 0.6000 handle.
On the downside, today’s decision has solidified the 0.5780 area as a robust tactical floor. It would likely require a significant and sustained de-escalation in Middle East tensions—thereby lowering the RBNZ’s immediate inflation fears—for the central bank to turn dovish enough to allow a break of the 0.5700 psychological support.
The NZD/USD is currently moving into a phase of broad consolidation. The pair is caught in a tug-of-war between two scenarios:
The Bullish Case: Persistent Dollar weakness combined with strengthening “hike” expectations in the domestic market could force a break higher toward 0.5900.
The Bearish Case: If the US Dollar remains “higher-for-longer” while global risk appetite remains limited, the Kiwi’s upside will stay capped, keeping the pair range-bound between 0.5780 and 0.5850.
AUD/NZD: The Divergence Play
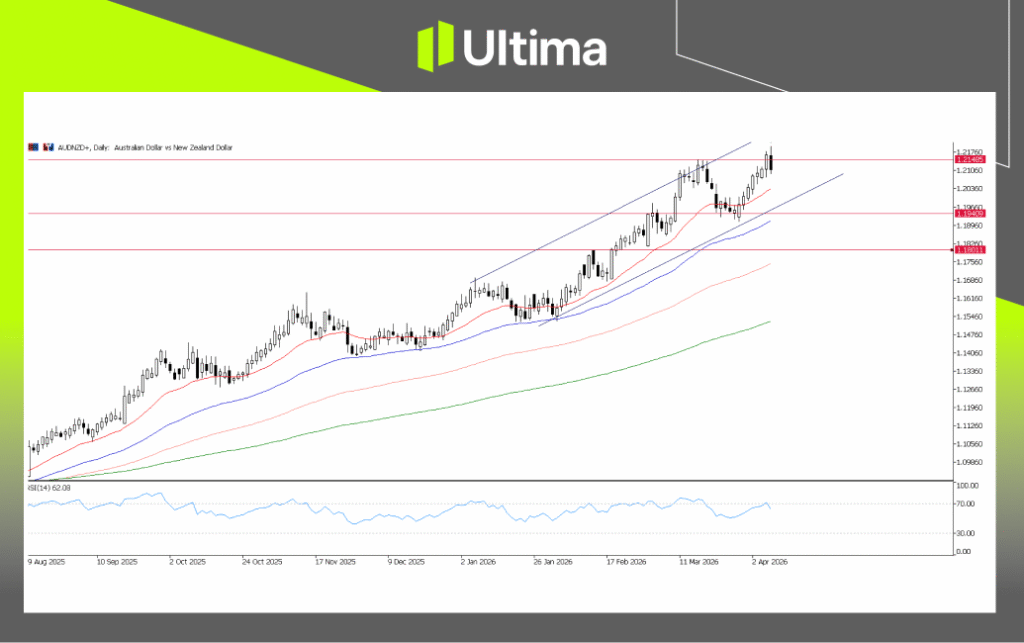
While NZD/USD consolidates, the AUD/NZD cross-rate tells a more aggressive story of policy divergence. Following the RBA’s recent hike to 4.10% and the RBNZ’s decision to hold at 2.25%, the pair has surged to a nearly 13-year high, testing the 1.2170 zone.
AUD/NZD, H4 Chart | Source: Ultima Markets MT5
AUDNZD undoubtedly on its uptrend, where the policy divergence is the major reason why AUDNZD is firmly on an uptrend. The RBNZ’s April meeting provided the catalyst for a pullback, but it is unlikely to change anything so far.
Given both countries’ similarity, the policy divergence has more impact on the currency exchange. As long as the 185 basis point yield gap remains in favor of the Aussie, any dips in AUD/NZD are likely to be bought by carry traders. Until any reversal pattern is formed or a significant change in the policy divergence outlook occurs, the uptrend remains.
Summary Outlook
The RBNZ’s hawkish pivot has successfully established a support floor for the Kiwi, effectively ending the narrative of further rate cuts in 2026. However, this domestic toughness faces two major global hurdles:
Against the AUD: The 185 basis point yield gap remains the dominant force. Even with a hawkish RBNZ, the Aussie’s 4.10% rate is simply more attractive for carry traders, keeping the AUD/NZD uptrend intact despite minor pullbacks.
Against the USD: While the RBNZ is talking “higher,” the US Fed is already “higher.” This keeps the NZD/USD trapped in a consolidation range, where any real upside depends more on a weakening Dollar than on New Zealand’s own policy.
Final Verdict: Expect the Kiwi to remain range-bound but resilient. The downside is now protected by the threat of a potential September hike, but the upside remains capped by superior yields in Australia and the US. Short-term bullish opportunities are best found in NZD crosses against weaker currencies like the EUR or CHF.
Disclaimer
Comments, news, research, analysis, price, and all information contained in the article only serve as general information for readers and do not suggest any advice. Ultima Markets has taken reasonable measures to provide up-to-date information, but cannot guarantee accuracy, and may modify without notice. Ultima Markets will not be responsible for any loss incurred due to the application of the information provided.
Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where access is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdiction.
By clicking ‘Acknowledge’, you confirm that you are entering this website solely on your own initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.