This website is managed by Ultima Markets’ international entities, and it’s important to emphasise that they are not subject to regulation by the FCA in the UK. Therefore, you must understand that you will not have the FCA’s protection when investing through this website – for example:
You will not be guaranteed Negative Balance Protection
You will not be protected by FCA’s leverage restrictions
You will not have the right to settle disputes via the Financial Ombudsman Service (FOS)
You will not be protected by Financial Services Compensation Scheme (FSCS)
Any monies deposited will not be afforded the protection required under the FCA Client Assets Sourcebook. The level of protection for your funds will be determined by the regulations of the relevant local regulator.
Note: UK clients are kindly invited to visit https://www.ultima-markets.co.uk/. Ultima Markets UK expects to begin onboarding UK clients in accordance with FCA regulatory requirements in 2026.
If you would like to proceed and visit this website, you acknowledge and confirm the following:
1.The website is owned by Ultima Markets’ international entities and not by Ultima Markets UK Ltd, which is regulated by the FCA.
2.Ultima Markets Limited, or any of the Ultima Markets international entities, are neither based in the UK nor licensed by the FCA.
3.You are accessing the website at your own initiative and have not been solicited by Ultima Markets Limited in any way.
4.Investing through this website does not grant you the protections provided by the FCA.
5.Should you choose to invest through this website or with any of the international Ultima Markets entities, you will be subject to the rules and regulations of the relevant international regulatory authorities, not the FCA.
Ultima Markets wants to make it clear that we are duly licensed and authorised to offer the services and financial derivative products listed on our website. Individuals accessing this website and registering a trading account do so entirely of their own volition and without prior solicitation.
By confirming your decision to proceed with entering the website, you hereby affirm that this decision was solely initiated by you, and no solicitation has been made by any Ultima Markets entity.
Ultima Markets does not have an establishment in Singapore and does not operate from Singapore.
Ultima Markets does not provide products or services to citizens or residents of Singapore, and account applications from Singapore citizens or residents will not be accepted.
If you are a citizen or resident of Singapore, please do not open an account or use Ultima Markets’ products or services.
By selecting “Acknowledge and Continue Browsing”, you confirm that you are accessing this website on your own initiative and that your access is not the result of any direct marketing, targeted advertising, solicitation, or promotional activity by Ultima Markets.
Nothing on this website constitutes an offer, solicitation, or promotion of products or services in any jurisdiction where such activity is prohibited. You are responsible for ensuring that your access to and use of this website complies with applicable local laws and regulations.
Silver price all time high in 2025. Learn why it broke out, how London tightness and deficits matter, and the key catalysts to watch this quarter.
Silver Price All Time High: What’s the Next Move?
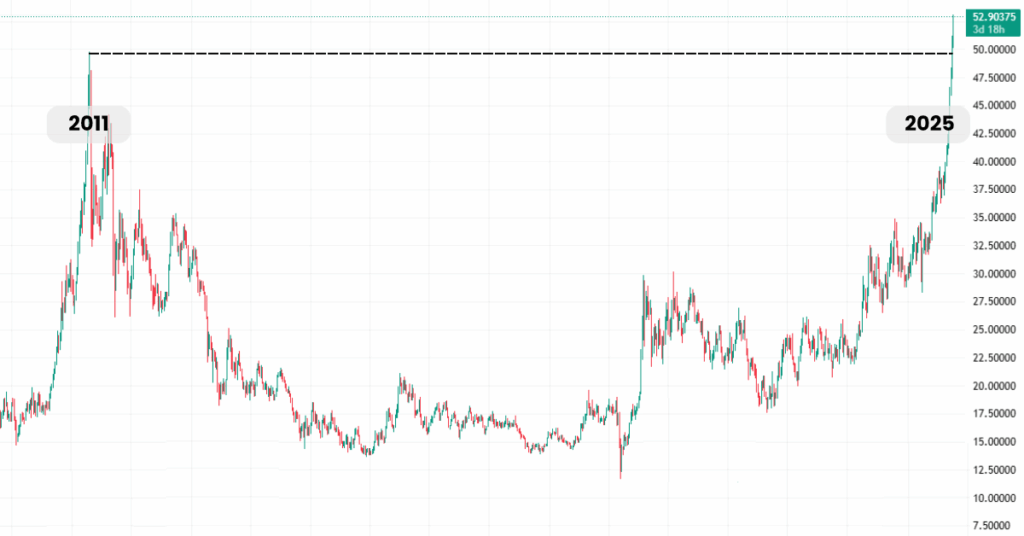
The silver price all time high is finally here. Between 13 and 14 October 2025, spot silver smashed through the old 1980 ceiling, first printing around $51.7/oz and then topping $52.5/oz in early London trade. The final burst wasn’t just “risk-off” sentiment; it was turbocharged by a historic London short squeeze alongside record-breaking gold.
Why “All Time High” Matters Now
When people say silver price all time high, they’re talking about the highest nominal USD price on major venues. The folklore line was the January 1980 spike near $50; in 2011 silver ran close but didn’t clearly break it. The October 2025 breakout turns that once-mythic top into a live pivot that markets will test on pullbacks.
What Pushed Silver Over The Top
1) A London Squeeze, Not Just a Narrative
Plumbing, not poetry, turned a strong rally into a sprint.
Borrowing costs spiked: one-month silver lease rates in London surged above 30% annualised, making it punitive to roll shorts and forcing rapid covering.
Regional dislocation: a London–New York premium widened (peaked near $3/oz last week; about $1.55/oz on Tuesday), and traders even air-freighted bars across the Atlantic to capture the spread.
2) Macro Tailwinds From Gold
Gold set fresh records the same sessions as haven demand met rising odds of policy easing. September also delivered the largest monthly inflow on record for physically backed gold ETFs, supercharging the broader precious-metals bid and helping the silver price all time high.
3) Structural Tightness: Deficits + Industry
This isn’t just momentum. Industrial use hit a record 680.5 Moz in 2024 (PV/solar, electronics, EVs, grid), while the market ran a ~149 Moz deficit and is projected to remain in deficit into 2025. Tight fundamentals mean squeezes bite harder and retracements find support sooner.
4) On-the-Ground Pressure From India
Ahead of Diwali, India, one of the biggest silver consumers saw spot shortages and premiums up to ~10% above international prices. Imports were down ~42% YTD (to August), and some silver products/ETFs paused new subscriptions due to high acquisition costs, amplifying the squeeze into London.
Was the 13–14 Oct short squeeze caused by the crypto crash?
Short answer: No. Same macro weather, different plumbing.
The crypto sell-off on 10–11 Oct contributed to a broader risk-off tone and a stronger haven bid. But silver’s vertical move was triggered by London market dynamics, not crypto flows. In other words, crypto set the mood; London’s own mechanics pulled the trigger.
What The New High Tells Us
$50 becomes the pivot. In a classic breakout, former resistance often becomes support. If the silver price all time high area holds on dips, the new range shifts higher.
Volatility cuts both ways. Silver’s market is far smaller than gold’s and moves faster on flows. Great on the way up, brutal on unwinds.
It’s not just gold’s shadow. The combination of haven demand + industrial pull + deficits is a different mix than prior spikes, giving this move deeper roots.
Key Dates And Levels To Remember
1980: legendary peak near $50 (nominal reference).
2011: big run that stalled just shy of the 1980 top.
13–14 Oct 2025:silver price all time high with ~$51.7 → $52.5+/oz, set amid a London squeeze and record gold.
What Could Move Silver Next
1) Rates, real yields, and the US dollar
Silver’s path is tightly linked to Fed expectations and real yields. A dovish tilt and easing real yields support precious metals; a hawkish pivot or upside surprises in inflation would do the opposite. Keep an eye on Fed communications into this month’s decision.
2) Section 232 and tariff policy
The US Section 232 “critical minerals” review (which includes silver, platinum, palladium) is a swing factor for trade routes and regional price spreads. A benign outcome could relax London tightness; adverse outcomes could re-tighten logistics and premiums.
Post-Diwali, watch whether premiums retreat. Persistently high premiums or recurring import frictions would keep nearby supply tight and support the silver price all time high narrative.
5) Industrial demand vs. deficits: The “Second Engine”
Track PV installations, electronics shipments, and grid capex. The Silver Institute pegged 2024 industrial demand at a record 680.5 Moz and a ~148.9 Moz deficit; supply responds slowly because ~70% of silver is mined as a by-product.
6) Gold’s leadership: ETFs and central banks
Silver often amplifies gold’s direction. The World Gold Council reported record monthly ETF inflows in September and a record quarter; if ETF or official-sector demand cools, silver usually feels it quickly.
7) Positioning, inventories, and exchange signals
Keep tabs on CFTC positioning, visible inventories, and dealer notes on deliverable good-delivery bars. Rising stocks + easing leases = cooler tape; tight stocks + firm leases = combustible (especially into month-end rolls).
8) Energy, mining margins, and supply shocks
Because silver is mostly a by-product, changes in copper/lead/zinc mine plans and energy costs can pinch or extend supply. Smelter/refinery disruptions or jurisdictional restrictions can tighten nearby availability without warning.
9) FX and China’s growth pulse
A weaker USD supports non-yielding assets; a sharp dollar rally is a headwind. China’s PMIs, credit impulse, and export policy matter twice: for global risk appetite and for industrial silver demand.
10) Street scenarios
Bank of America now sketches $65 by end-2026 (deficits + lower real rates) but warns of near-term correction risk after the squeeze. Use this as context, not guidance.
Final Thoughts
The silver price all time high isn’t just a headline, it’s the product of macro fuel, market mechanics, and real-world demand. With $50 now the line to watch, expect two-way volatility as squeeze dynamics fade and fundamentals take centre stage.
Share Now
Disclaimer:This content is provided for informational purposes only and does not constitute, and should not be construed as, financial, investment, or other professional advice. No statement or opinion contained herein should be considered a recommendation by Ultima Markets or the author regarding any specific investment product, strategy, or transaction. Readers are advised not to rely solely on this material when making investment decisions and should seek independent advice where appropriate.
Thank you for visiting the Ultima Markets website. Please note that this website is intended for individuals residing in jurisdictions where access is permitted by law. Ultima and its affiliated entities do not operate in your home jurisdiction.
By clicking ‘Acknowledge’, you confirm that you are entering this website solely on your own initiative and not as a result of any specific marketing outreach. You wish to obtain information from this website based on reverse solicitation principles, in accordance with the applicable laws of your home jurisdiction.